Hey folks,
Here’s a fun one. In 17 countries right now, the government’s parting gift is a tax bill on money you haven’t realised yet.
IMI Daily ran a roundup this week counting exactly who does this and how. I’ve gone through it and pulled out what actually matters if your plan involves leaving a country someday, which, if you’re reading a FIRE and geo-arbitrage newsletter, it almost certainly does.
If you’re new here: I retired at 35 through options trading and geo-arbitrage, and I write about both here. Subscribe if you want this landing in your inbox.
What an exit tax actually is
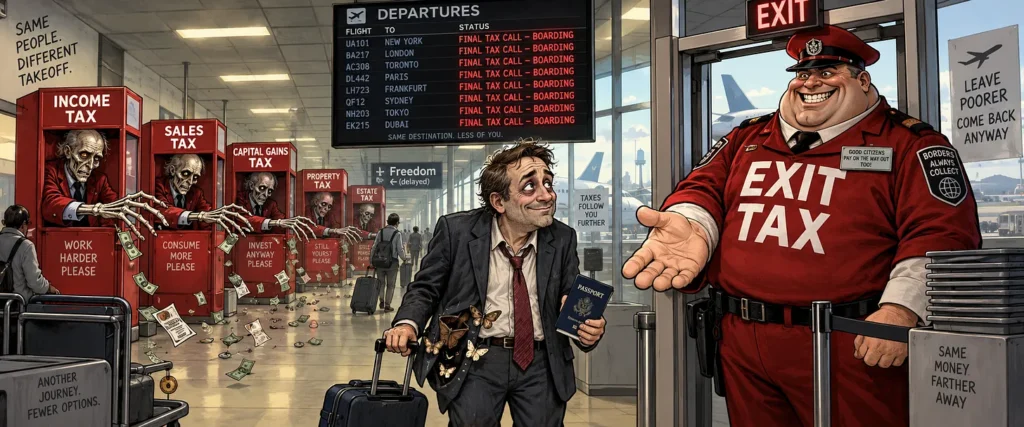
An exit tax triggers the day you stop being a tax resident of a country. The government treats it as if you sold every appreciated asset you own at that moment, even though you didn’t sell anything and have no cash sitting around to cover the bill. You get taxed on the gain as if it were realized income, and then you’re free to leave.
So, yup, just pretend that you sold your artwork, and your real estate today, then give us X percent of that number as a little thanks for leaving present to your favourite government tax department.

The people this hits hardest are exactly the people building wealth through investing and planning to retire somewhere cheaper. You spend a decade or more compounding a portfolio, decide it’s time to go live in Panama or Portugal or wherever, and the country you’re leaving hands you an invoice for the privilege on your way out the door. Wait, didn’t you earn your money, pay tax on that money, then risk that money through investment, then yes pay more tax on the gains the money made and on and on it goes? What’s this additional tax for? Because someone chose to leave?
Who’s already doing this
The list splits into three groups.
No wealth threshold at all. Think of this as “it doesnt matter, pay up.” Regardless of how much your net worth is, you pay!

Austria, Belgium, Canada, Australia, South Africa, Israel, and New Zealand will tax you on departure regardless of how much you’re worth. New Zealand’s version is currently narrow (it only catches people who elected a specific accounting method for foreign investments), but Budget 2026 proposes extending it to everyone, with draft legislation expected this month. As a Kiwi, I’m watching that one closely.
Threshold-based. Denmark, Norway, Japan, Poland, France, and Spain only apply the tax once you cross a net worth or holding-value line. Denmark’s threshold is the lowest in the world at roughly DKK 100,000. Norway’s is the toughest to escape once you’re caught: 70% of any foreign dividends you receive afterward get clawed back to fund your exit tax debt, and your foreign tax credits disappear too. Spain, where I live, sets the bar at €4 million in investments or a 25%+ stake worth over €1 million, with a residency test of 10 out of the previous 15 years. I‘m actually on board with something similar to this. Perhaps not as aggressive as Norway, but similar.
Shareholder-only. Germany, the Netherlands, and South Korea currently target people with meaningful equity stakes in specific companies rather than general portfolios, though South Korea is about to widen that considerably.

The odd one out: the United States. The US taxes citizenship itself, not just residency, under Section 877A. Renounce your citizenship as a “covered expatriate” (net worth over $2 million, or average tax liability above roughly $211,000 over five years, or you simply failed to certify five years of clean tax compliance) and you owe capital gains tax on the deemed sale of your entire portfolio above a $910,000 exclusion. Your IRAs get treated as fully distributed on the spot. It’s the most aggressive version of this tax on the planet, and it’s aimed at Americans who want out entirely, not just Americans who move abroad. This is horrible as a non US Citizen looking in. I can speak with alot of US folks who want to leave but they know that the US tax man is going to be hunting them for the rest of their days like that fella Jason in the hockey mask. Relentless.
Who’s circling the idea next
This list is growing, not shrinking. The UK Chancellor floated a 20% “settling up charge” in late 2025 that would have raised an estimated £2 billion a year. Honestly!!! Like a tab at a pub. Thanks Rachel (The Chancellor), how much do it owe ya? Well Andy, that was 15 years on oppressive taxes here in the UK, less travel mobility and a decline health system, that will be a cheeky 20% of the net worth, thanks mate!!!!

It got shelved after roughly 150 business leaders objected, but Brexit removed the EU free movement issue that used to make this politically awkward, and the idea keeps resurfacing. South Korea confirmed its exit tax expands to foreign stocks from January 2027. The Netherlands’ parliament has instructed its government to develop broader exit tax rules. Poland’s version is currently in front of the EU’s top court over whether it’s even legal.
None of this is theoretical for the FIRE crowd. It’s aimed directly at people with investment portfolios who move countries, which is the entire strategy this newsletter is built around. I like to call this to toll gate. Basically, as taxes go up within your country, governments with any sense are realising that capital has wings and will just leave to greener pastures… like every rich person in the UK who is currently living permanently in the UAE, Italy or Greece with all their cash. So to clip the ticket one last time countries are building their toll gates, where they get to rob you one last time.
Why this actually matters to you
If you’re building toward FIRE through a brokerage account and you’re currently tax resident in one of these countries, your net worth is, by design, a pile of unrealized gains. That’s the whole point of buy-and-hold investing. It’s also exactly what an exit tax is built to catch.
The nasty part is timing. Every source on this agrees: the bill you’d pay today is the smallest one you’ll ever pay, because unrealized gains only grow from here, and once you actually trigger the tax (by ending your residency), it’s too late to do anything about it. Any restructuring, gifting, or timing strategy has to happen before that date, not after.
This is also a trap hiding inside investor visa programs, which a lot of geo-arbitrage plans lean on. The US EB-5 program can pull you into covered expatriate status. New Zealand’s Active Investor Plus visa can create its own exit charge down the line. Quebec’s investor program triggers Canada’s departure tax. If your retirement plan involves a golden visa or investor visa somewhere, check whether the country you’re leaving, not just the one you’re entering, has an exit tax and what your visa does to your residency clock there. Gosh it almost feels like if you have a few bob, the government is out to rob you at every turn. Like your being hunted lol.
What you can actually do about it, legally
Know your residency clock before you’re close to it. Most of these taxes only apply once you’ve been tax resident for a set number of years (Spain: 10 of the last 15, Norway: 5 of the last 10, France: 6 of the last 10, Germany: 7 of the last 12, Japan: 5 of the last 10). If you leave before you cross that line, the tax often doesn’t apply to you at all. This is a real argument for not overstaying in a high-tax country once you’ve locked in your FIRE number.
Move to the EU/EEA or a treaty country if you have the choice. Nearly every regime above offers automatic or requestable deferral for moves within the EU/EEA, sometimes indefinitely, sometimes with no collateral required. Move to Dubai, Singapore, or the Caribbean instead, and you’re far more likely to owe the full bill immediately. If you’re weighing destinations and exit tax exposure is on the table, this is a genuinely material factor.

Do your restructuring before you trigger the tax, not after. Asset restructuring, gifting to a spouse or family member in a lower-tax position, multi-year gain averaging, and disposal timing all have to happen while you’re still resident. The moment your residency ends, every one of these options closes.
Get advice on both ends, not just the destination. David Lesperance, quoted in the IMI Daily piece, put it well: study the country you’re leaving as closely as the one you’re moving to. Most people researching a move to Portugal or Panama spend zero hours researching what their current country charges them to leave.
Don’t assume a tax residency certificate protects you. Several of these regimes look at your actual physical presence and center of life, not just a piece of paper from a low-tax jurisdiction. If your current country can show you never really left, the exit tax clock never started, and you’re still on the hook.
Hit comment and let me know: does your current country have one of these on the books? I’m curious how many of you are sitting on this without realizing it.
Cheers,
Andy
Dragon stone (San Juan de Gaztelugatxe)
Spain

Be an Adult. This newsletter is for education, not tax or legal advice. Exit tax rules vary by country, change frequently, and depend on your specific residency and asset history. Speak to a licensed cross-border tax advisor before making any decisions about your residency or citizenship.